
Reports according to Vietnam Accounting Standard
Requirements
This tutorial requires the installation of the following applications/modules:
The reports cluster according to Vietnam Accounting Standard is located in the Viindoo Accounting app for Vietnamese companies. This article is for accountants and chief accountants who keep the books of a company under Circular 99/2025/TT-BTC or Circular 133/2016/TT-BTC. This set of financial reports includes:
Statement of Financial Position;
Profit and Loss;
Cash Flow Statement.
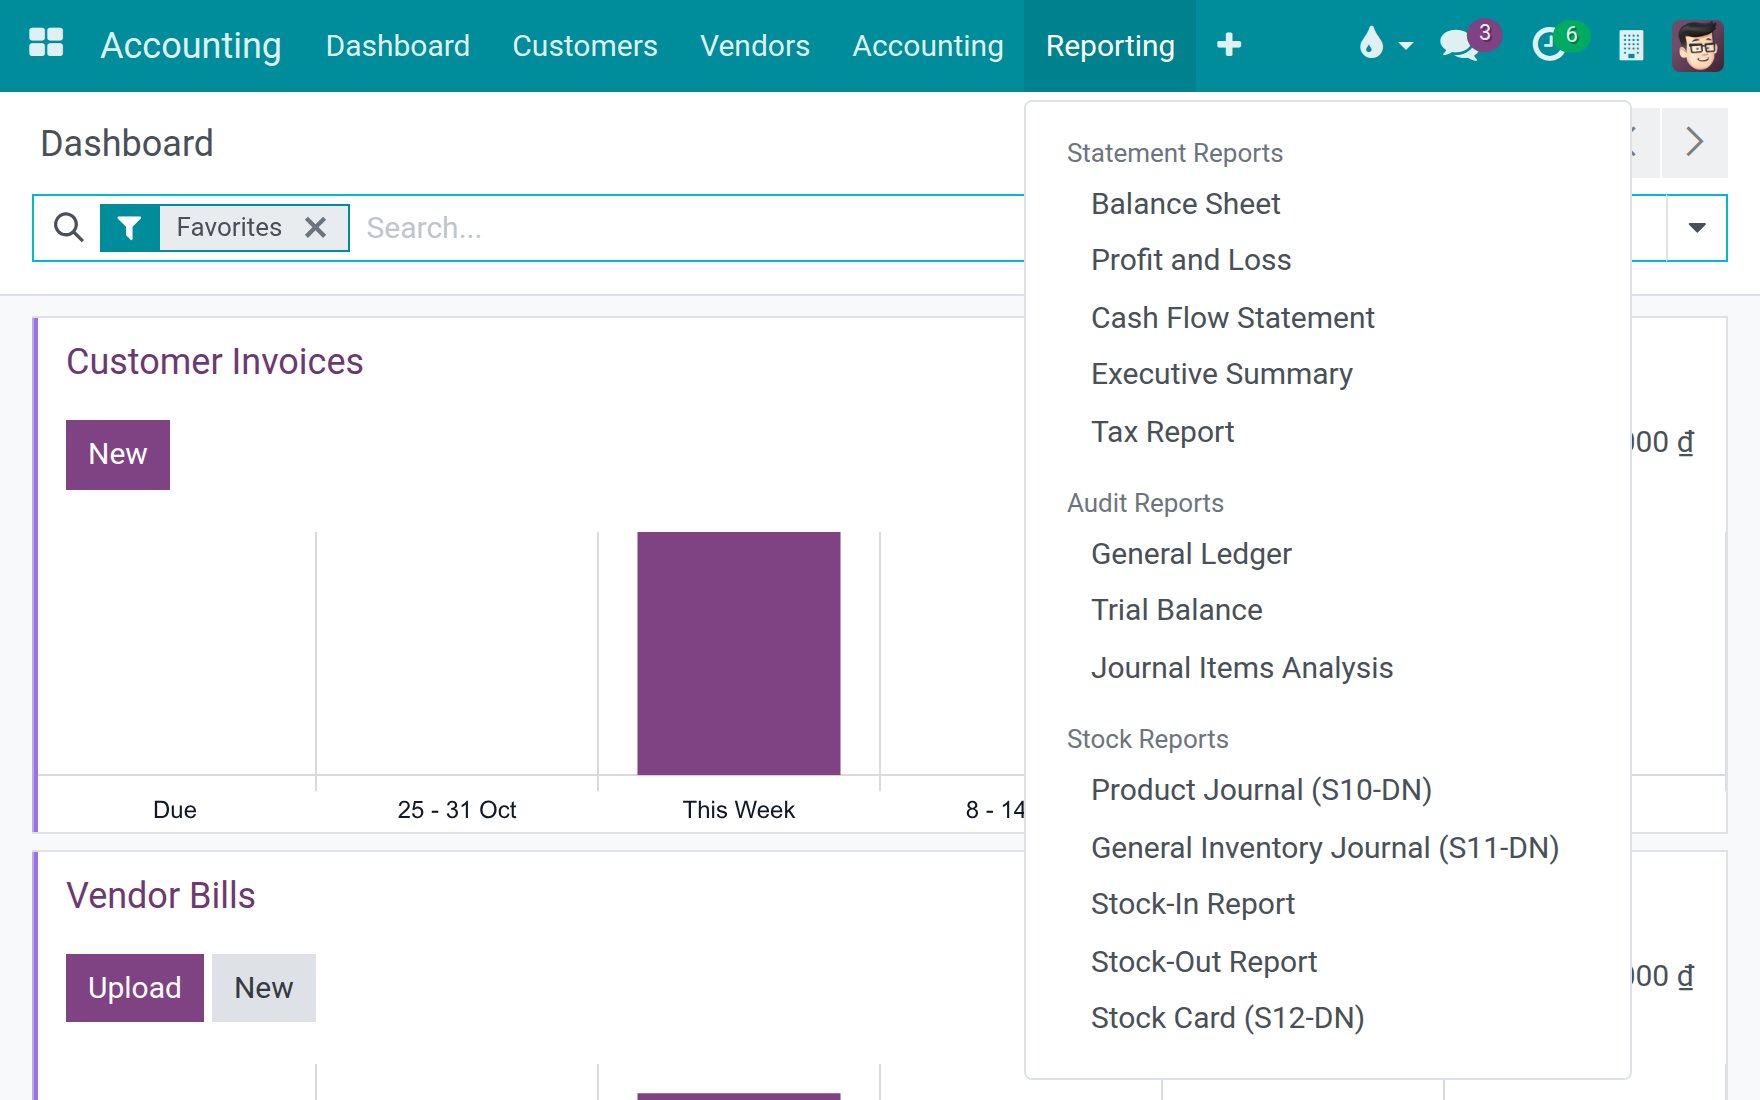
Currently, the software supports some general reports used for multiple countries. To use the report set according to the Vietnamese accounting standards, you can access Accounting > Reporting > Statement Reports.
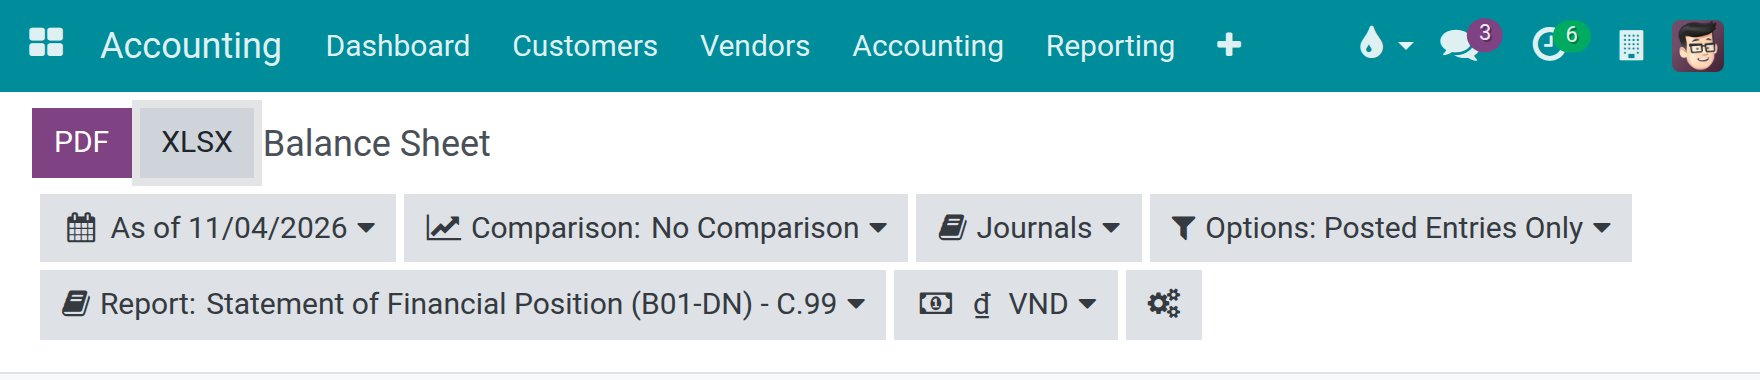
At the report viewing interface, you can select the Vietnamese accounting standard report template with the Report selector. It offers the forms of the chart of accounts of the company:
Statement |
Circular 99/2025/TT-BTC |
Circular 133/2016/TT-BTC |
|---|---|---|
Statement of Financial Position |
Statement of Financial Position (B01-DN) - C.99 |
Balance Sheet (B01a-DNN) and Balance Sheet (B01b-DNN) |
Profit and Loss |
Profit and Loss (B02-DN) - C.99 |
Profit and Loss (B02-DNN) |
Cash Flow Statement |
Cash Flow Statement (B03-DN) - C.99 |
Cash Flow Statement (B03-DNN) |
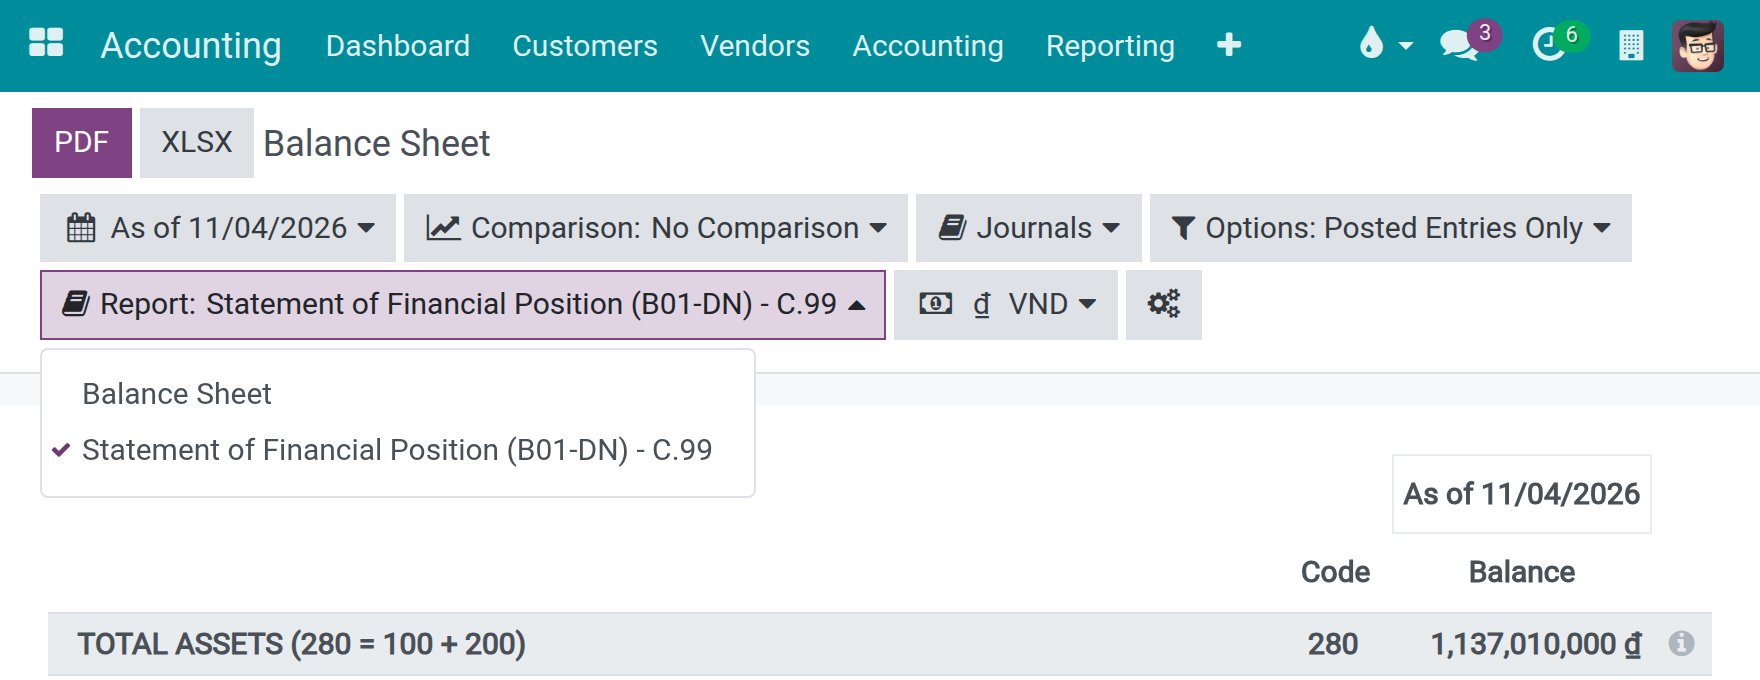
The screenshots of this article show the demo data of a company on the Circular 99/2025/TT-BTC chart of accounts, and of a company on the Circular 133/2016/TT-BTC chart where the form of that chart is the subject.
Statement of Financial Position (B01-DN)
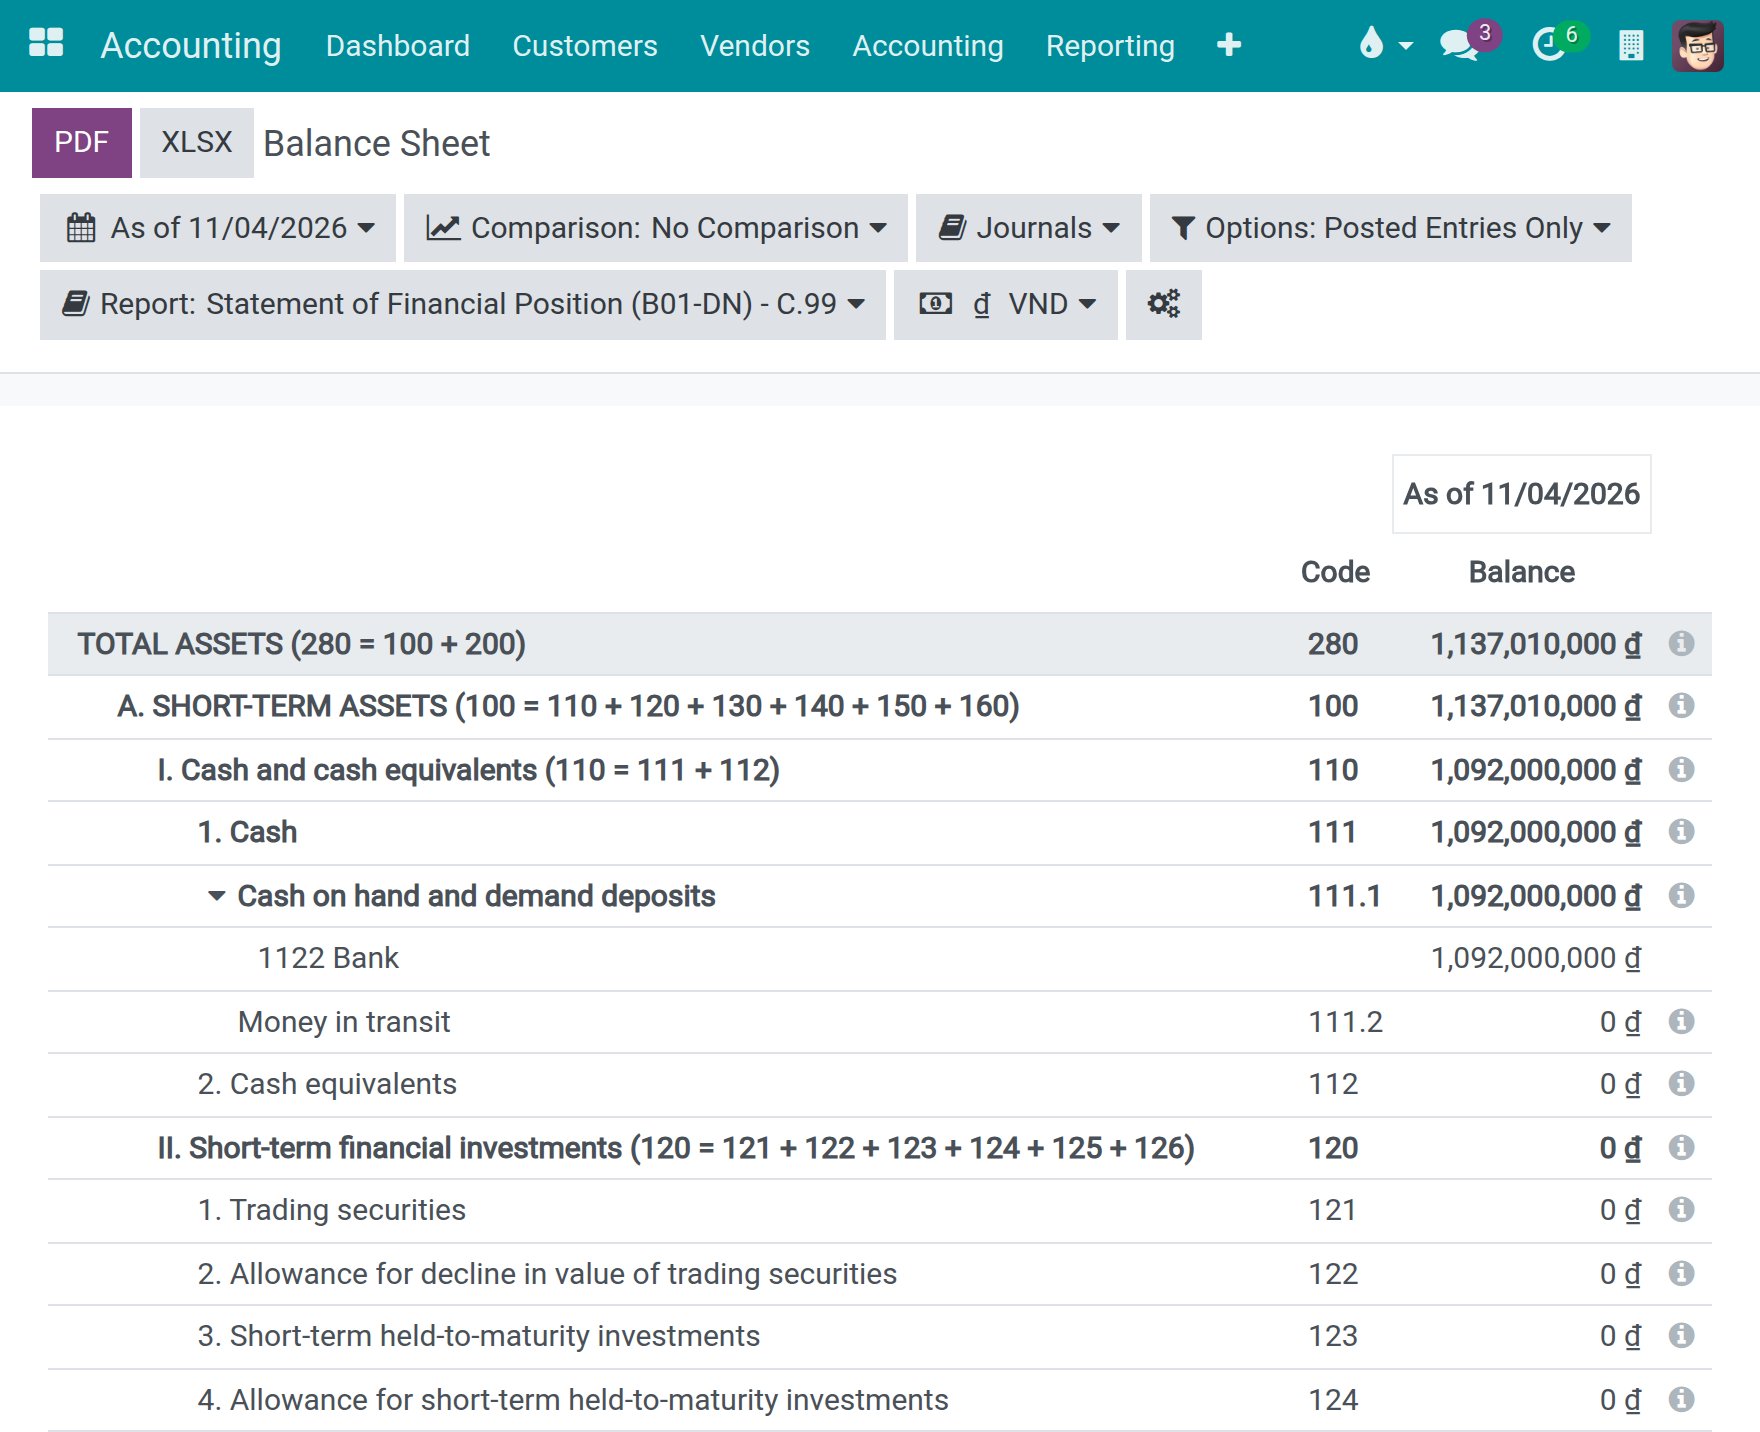
The Statement of Financial Position reflects the enterprise’s assets and equity at a certain point in time. The line codes below are those of the B01-DN form of Circular 99/2025/TT-BTC; the codes of the B01a-DNN and B01b-DNN forms of Circular 133/2016/TT-BTC are given where they differ.
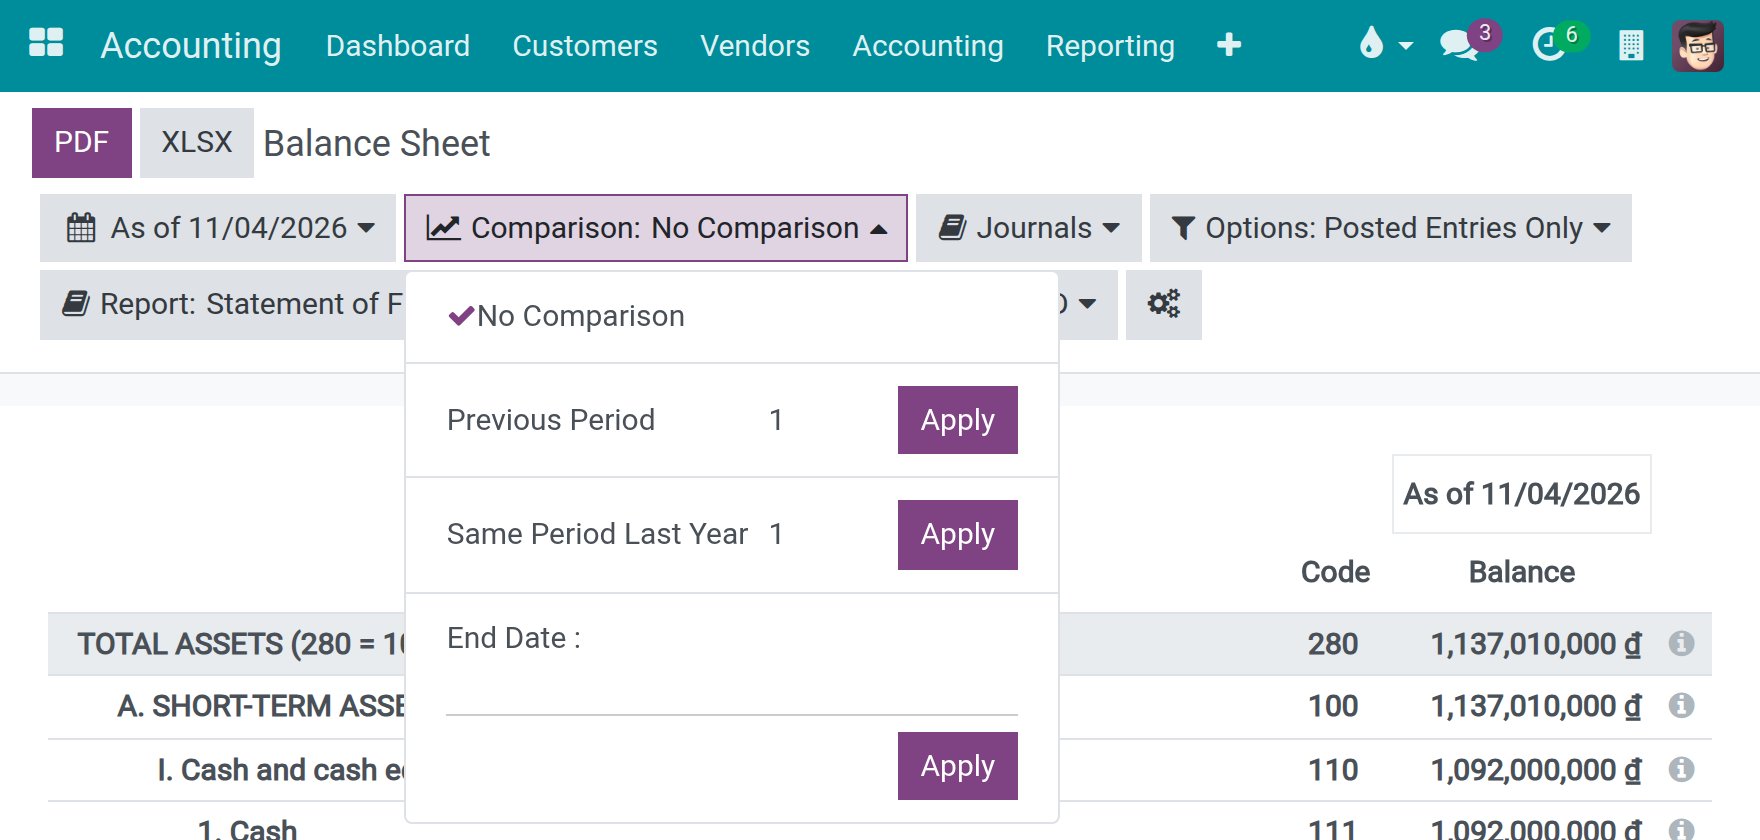
You can flexibly choose how to view the report with different criteria such as No Comparison, Comparison with previous period/same period last year, or custom criteria to have an overview and easy for the analysis of the data creation.
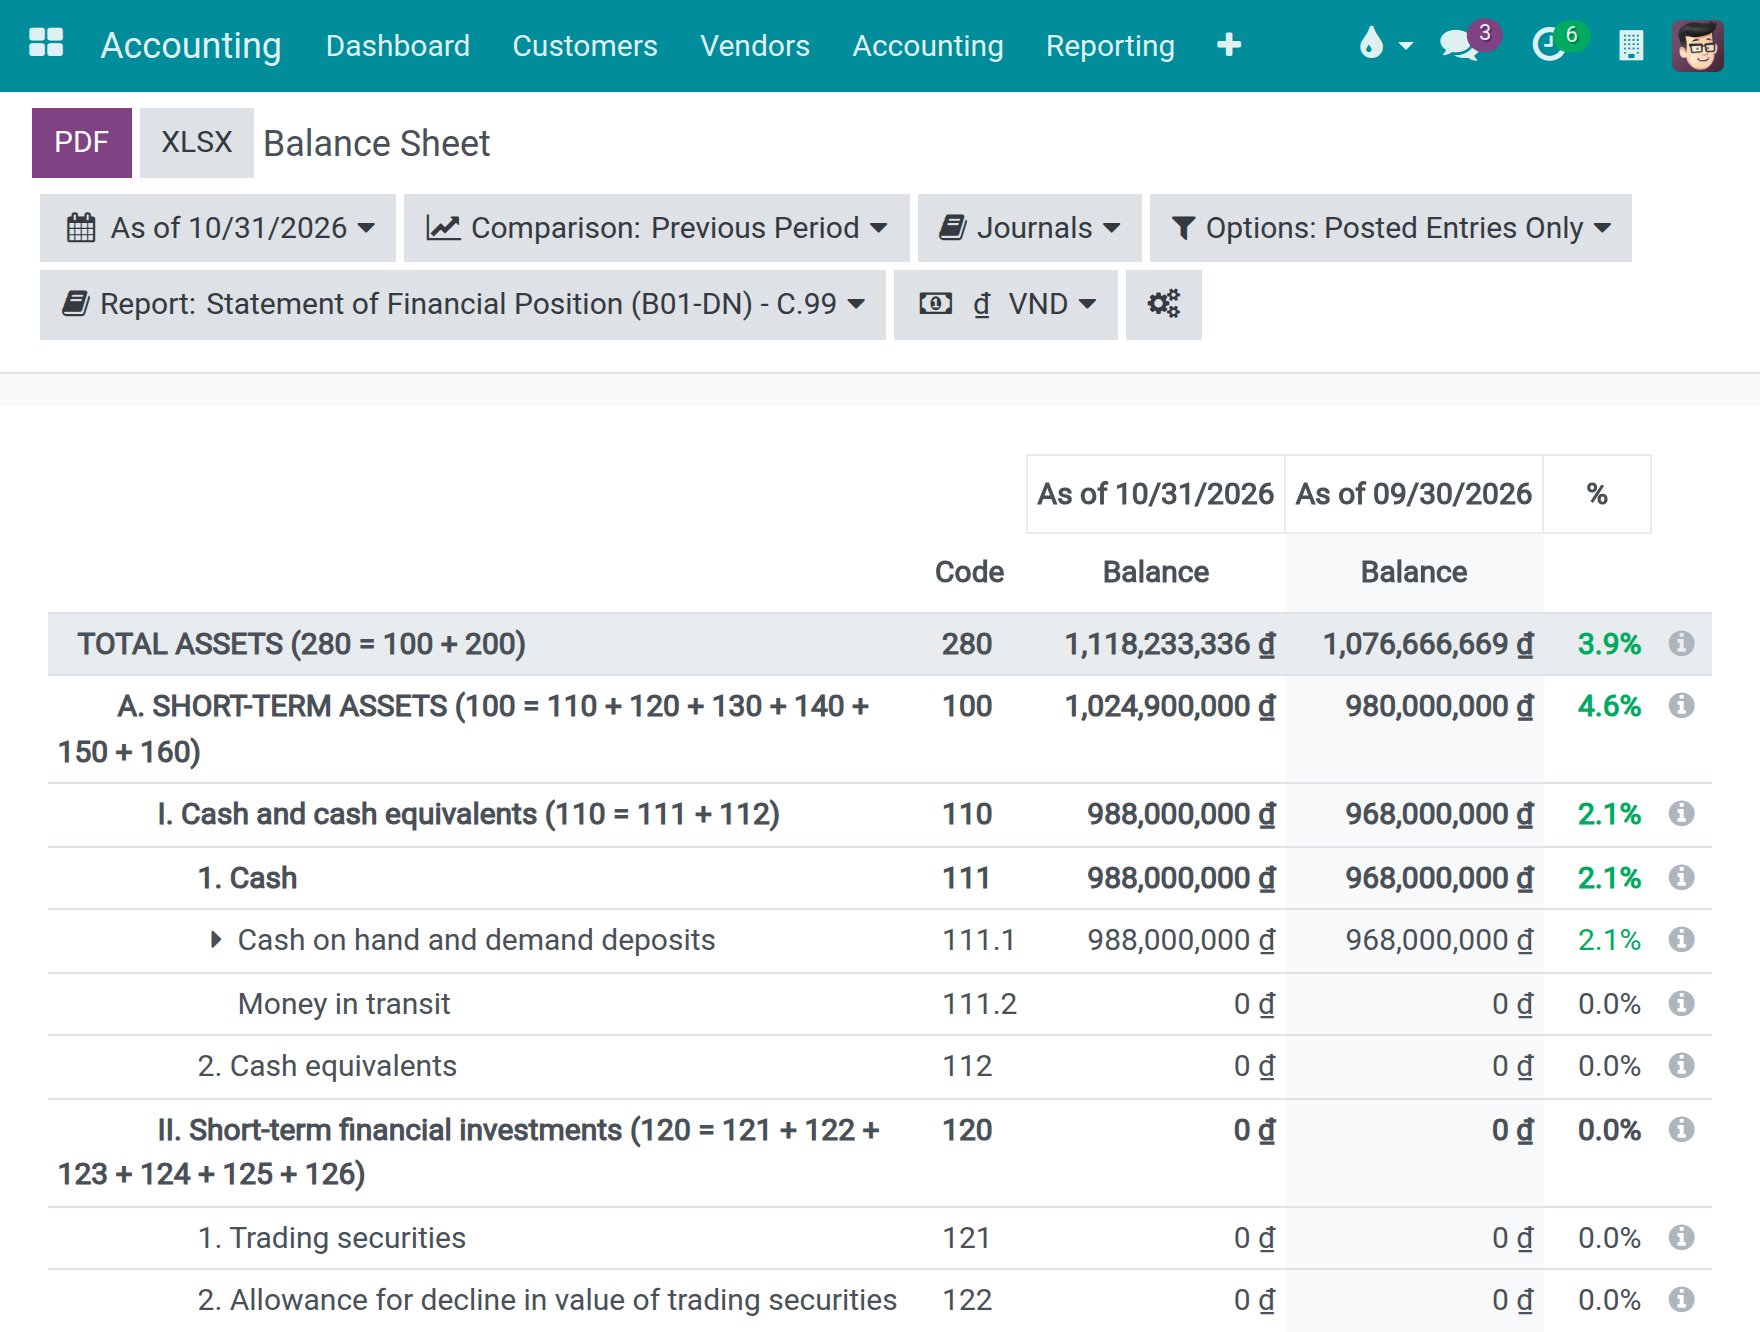
Cash per account
Line 111.1 (Cash on hand and demand deposits) is built account by account: unfold it to see each cash and bank account on its own row. An account with a debit balance counts as cash. An account whose balance is negative is never netted against the other accounts: it does not lower the cash, and its amount is shown as a bank overdraft (see below).
Line 111.2 (Money in transit) holds the money-in-transit account and the internal transfer account. They keep their sign, so a credit balance reduces the line.
Bank overdrafts
A bank account in overdraft is shown as a loan, under Bank overdrafts: line 321.2 on B01-DN, 316.2 on B01a-DNN and 416.2 on B01b-DNN. It is part of the short-term borrowings line (321, 316 and 416 respectively). In the example below, the account Bank 2 (overdraft) has a credit balance of 99,000,000, which line 321.2 shows next to the bank loan of 500,000,000 of line 321.1.
Unmatched bank statement lines
Bank statement lines that are not matched yet sit on the bank suspense account. The statement shows them instead of leaving them out:
a line of money received goes to other payables: line 320 on B01-DN, 315 on B01a-DNN and 415 on B01b-DNN;
a line of money paid out goes to line 137 (Shortages awaiting settlement) on B01-DN, 135 on B01a-DNN and 134 on B01b-DNN.
In the example, the money paid out that is not matched yet is 8,000,000 on line 137; unfold the line to see the bank suspense account behind it.

The money received that is not matched yet is 25,000,000 on line 320, next to the bank overdraft on line 321.2.
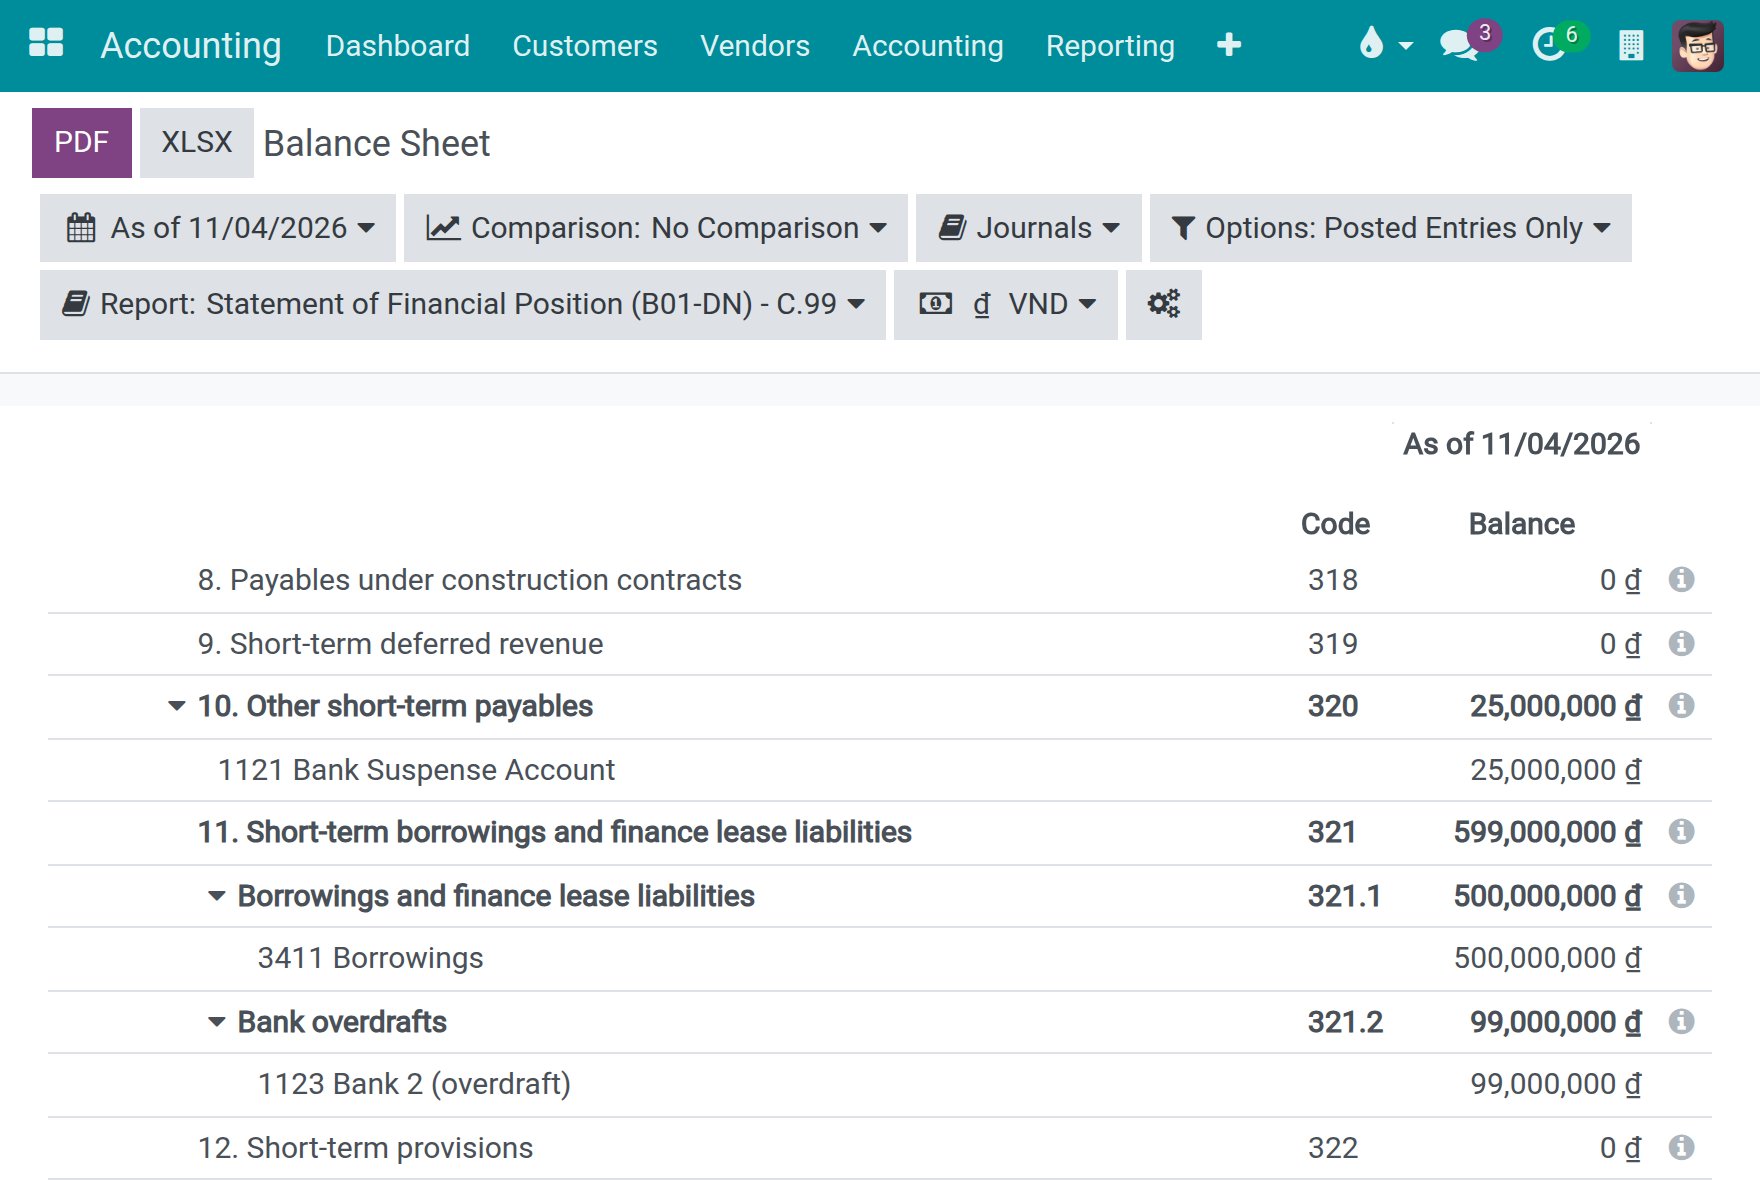
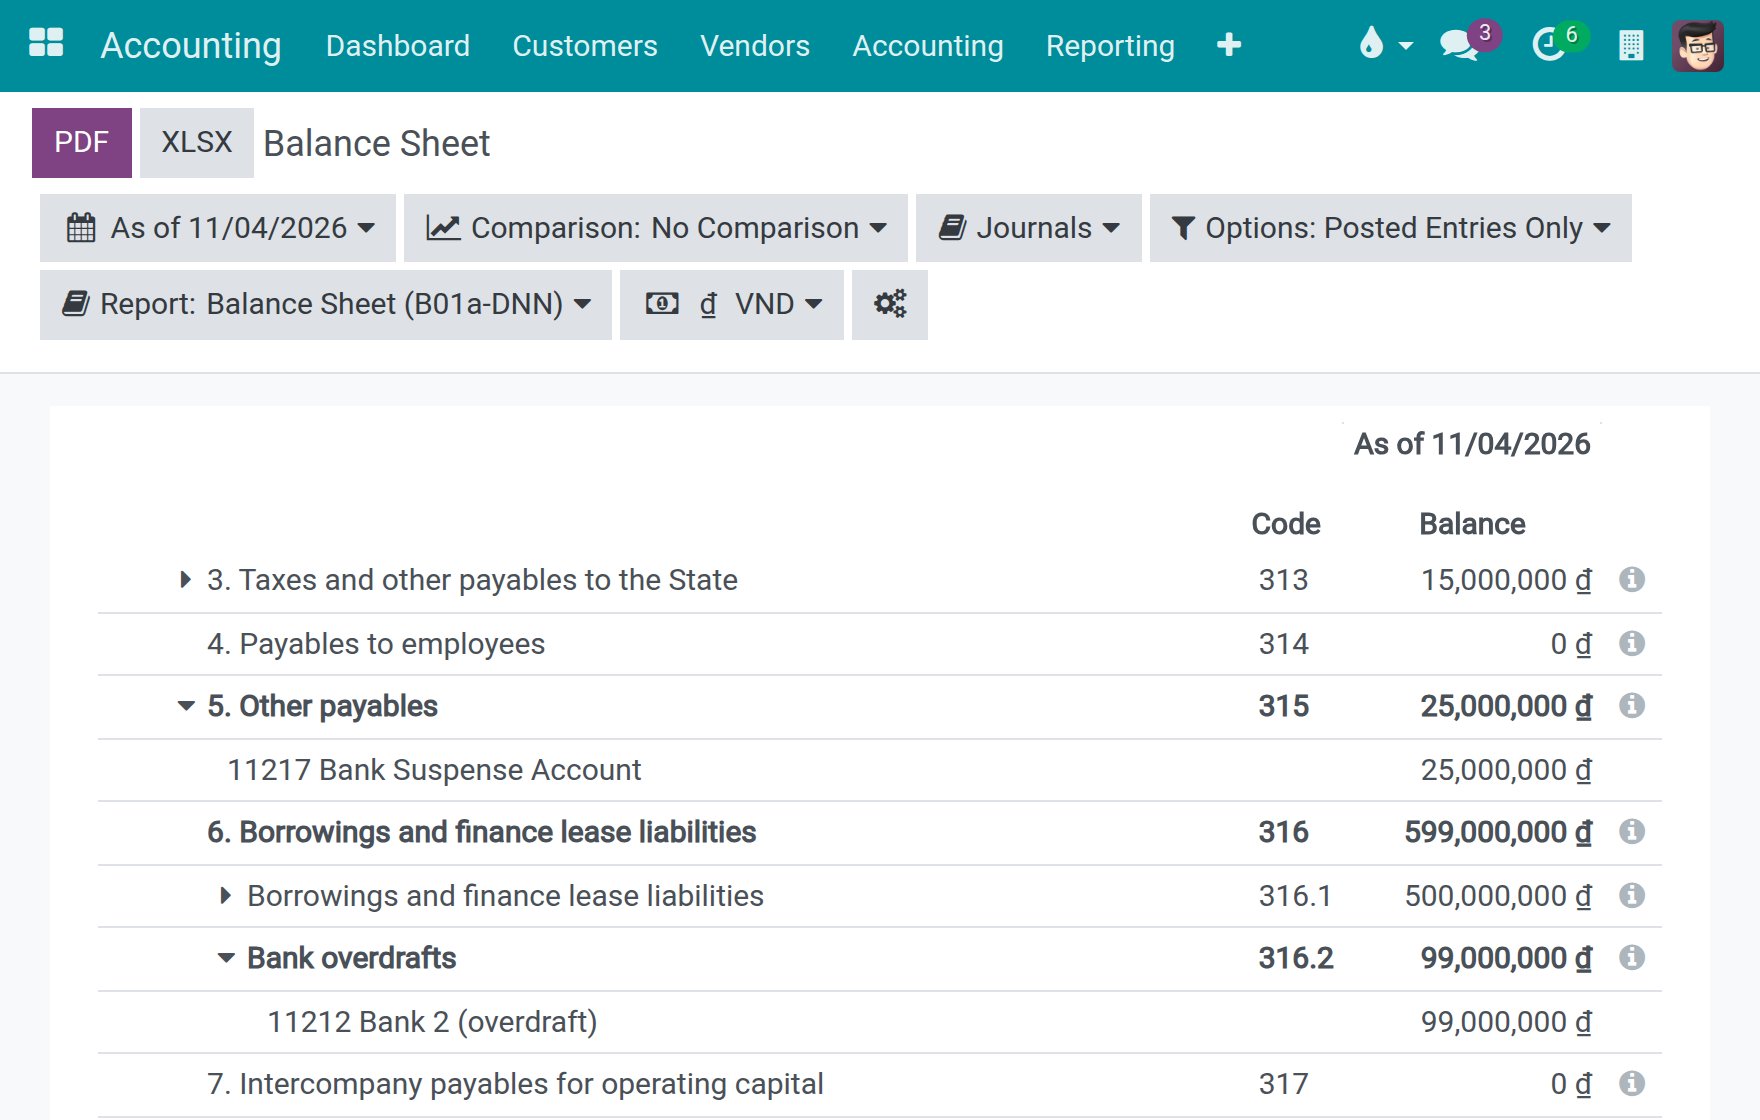
On a company that uses Circular 133/2016/TT-BTC, the same figures are on the lines of the B01a-DNN form, where line 315 holds the other payables and line 316.2 the bank overdrafts.
Preparer’s note
At the bottom of the Statement of Financial Position (B01-DN) - C.99, under line 420b, the report prints a note headed Preparer’s note. It is not part of the official B01-DN form. It tells the reader that, for seven pairs of short-term and long-term indicators (codes 133/214, 135/215, 314/333, 316/334, 317/336, 320/338 and 322/343), the balance arising from entries without a payment term is shown entirely under the short-term indicator, so the long-term indicator may be zero or lower than the actual amount. It adds that the company must disclose its actual classification principle in the Notes to the Financial Statements (B09-DN).
The note only appears on this report; the Statement of Financial Position forms of Circular 133/2016/TT-BTC, the Profit and Loss and the Cash Flow Statement do not carry it.

Profit and Loss (B02-DN)
To see the revenue, cost, or profit targets, you will use the B02-DN form. On a company that uses Circular 133/2016/TT-BTC, the form is Profit and Loss (B02-DNN).
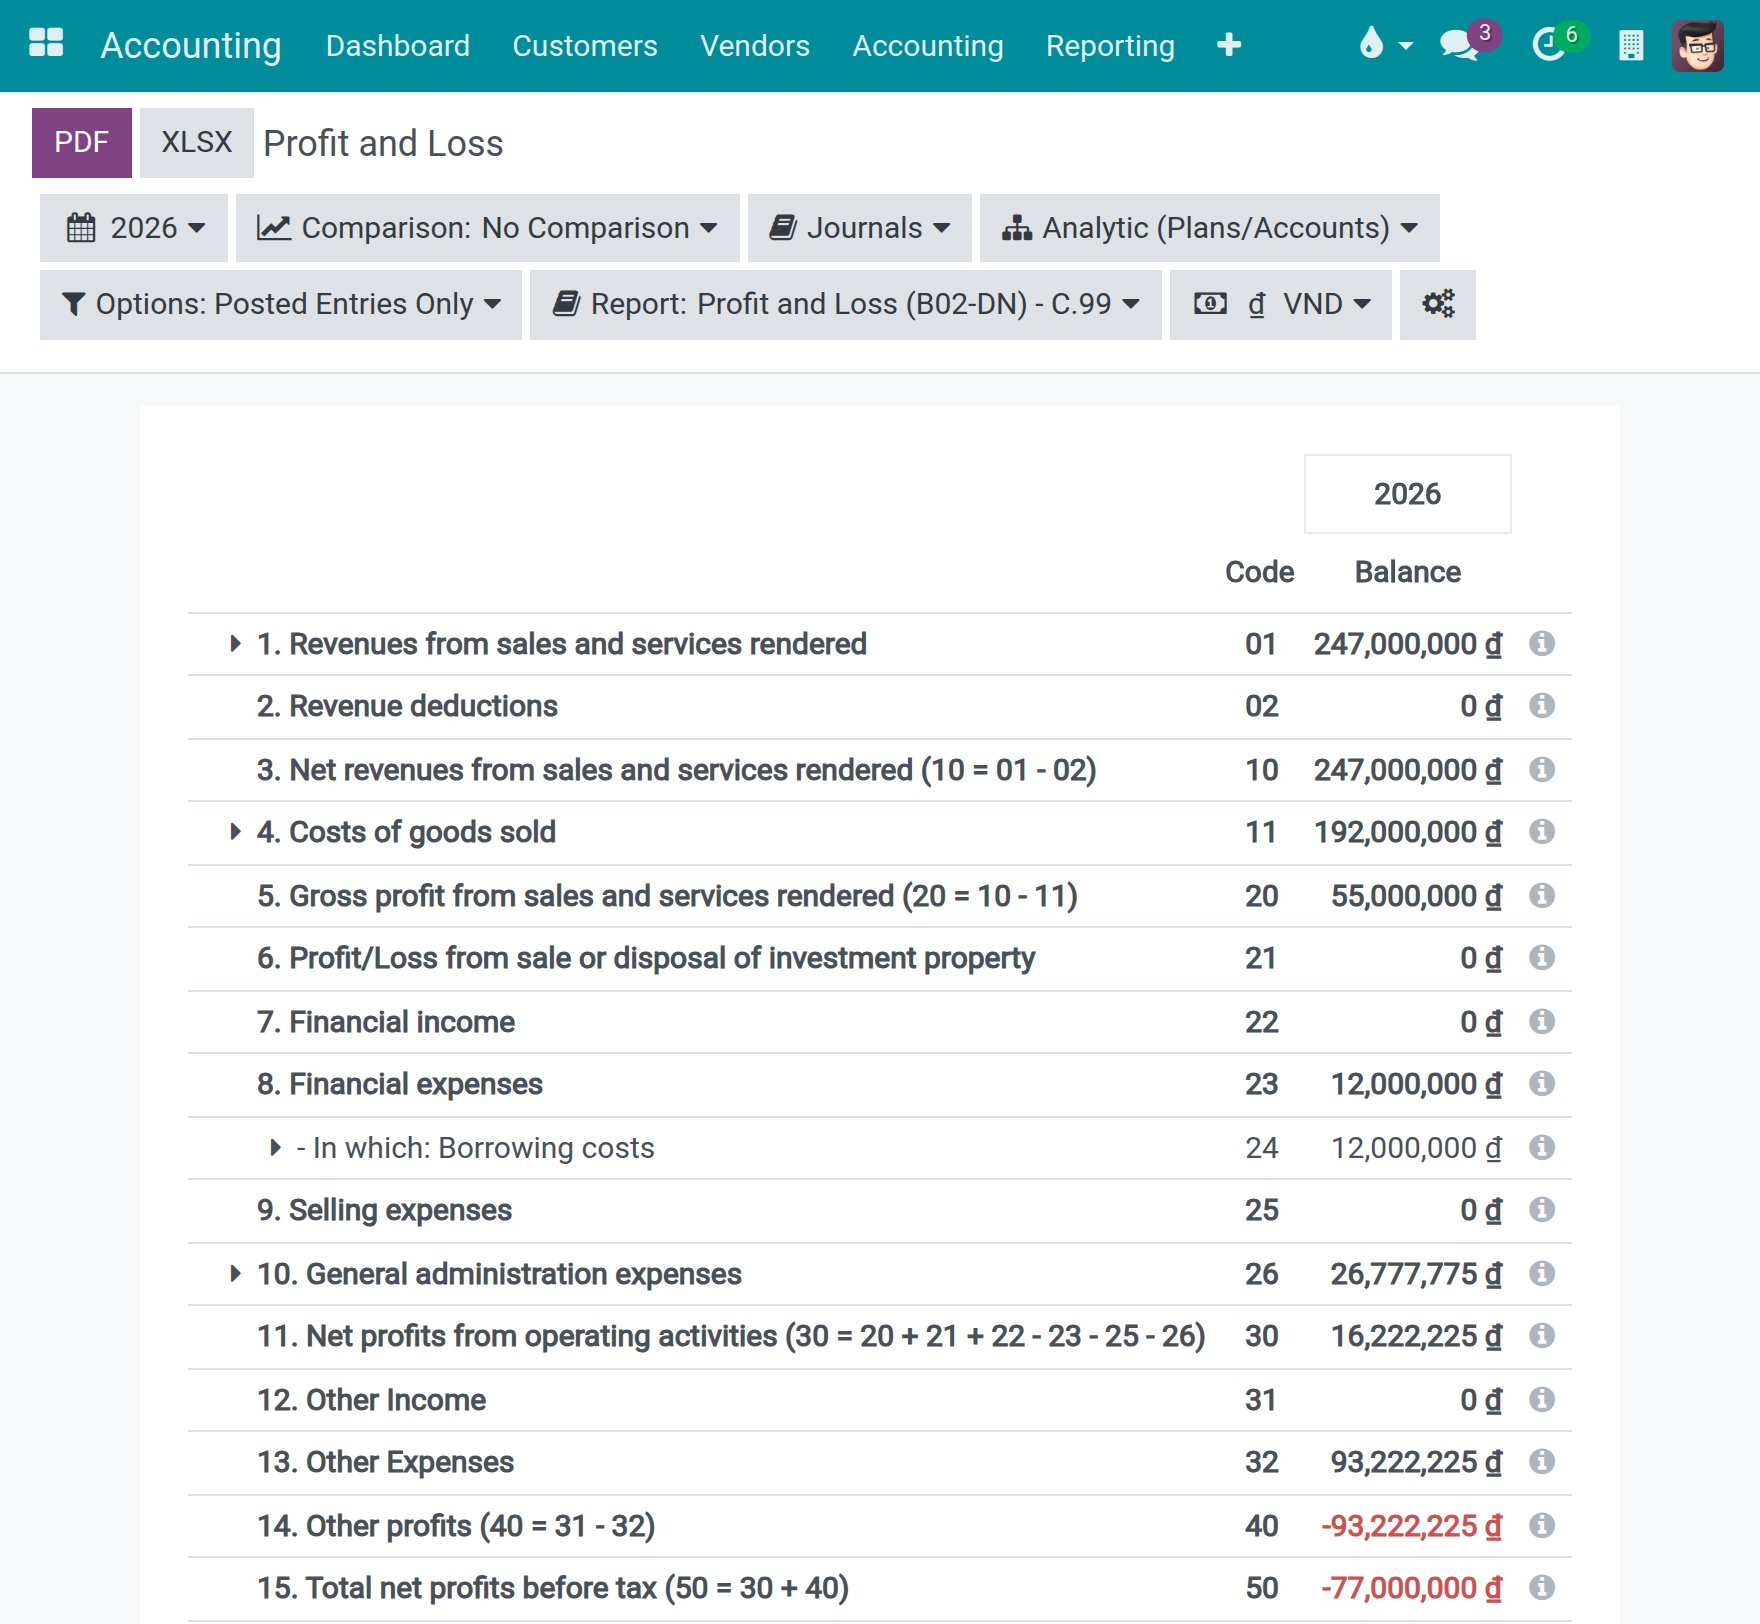
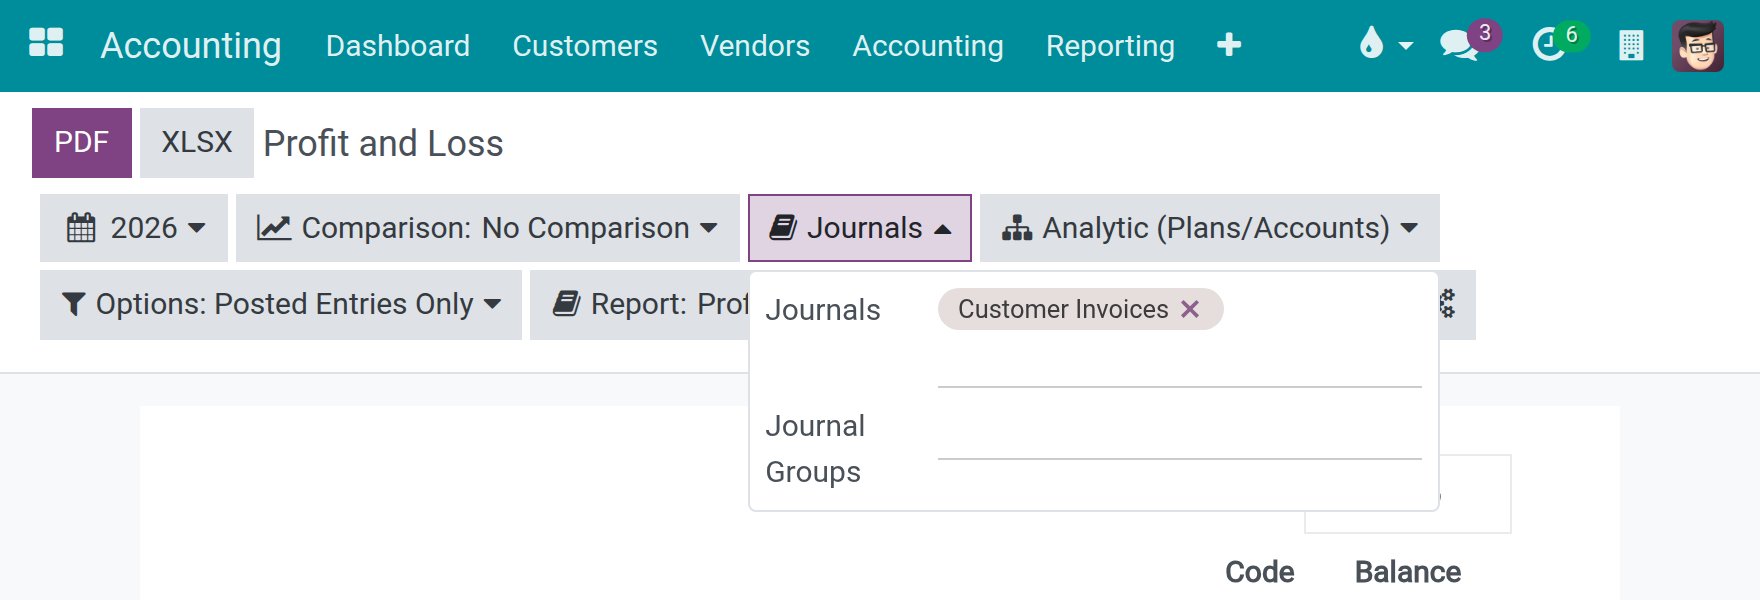
Choose to display information on this report by journal. For example: if you select the Customer invoices journal, the data displayed on the report will only show the items related to revenue.
Cash Flow Statement (B03-DN)
This report reflects information related to the fluctuation of cash. Under Circular 99/2025/TT-BTC the form is Cash Flow Statement (B03-DN) - C.99; under Circular 133/2016/TT-BTC it is Cash Flow Statement (B03-DNN). The line codes below are those of B03-DN.
Operating activities
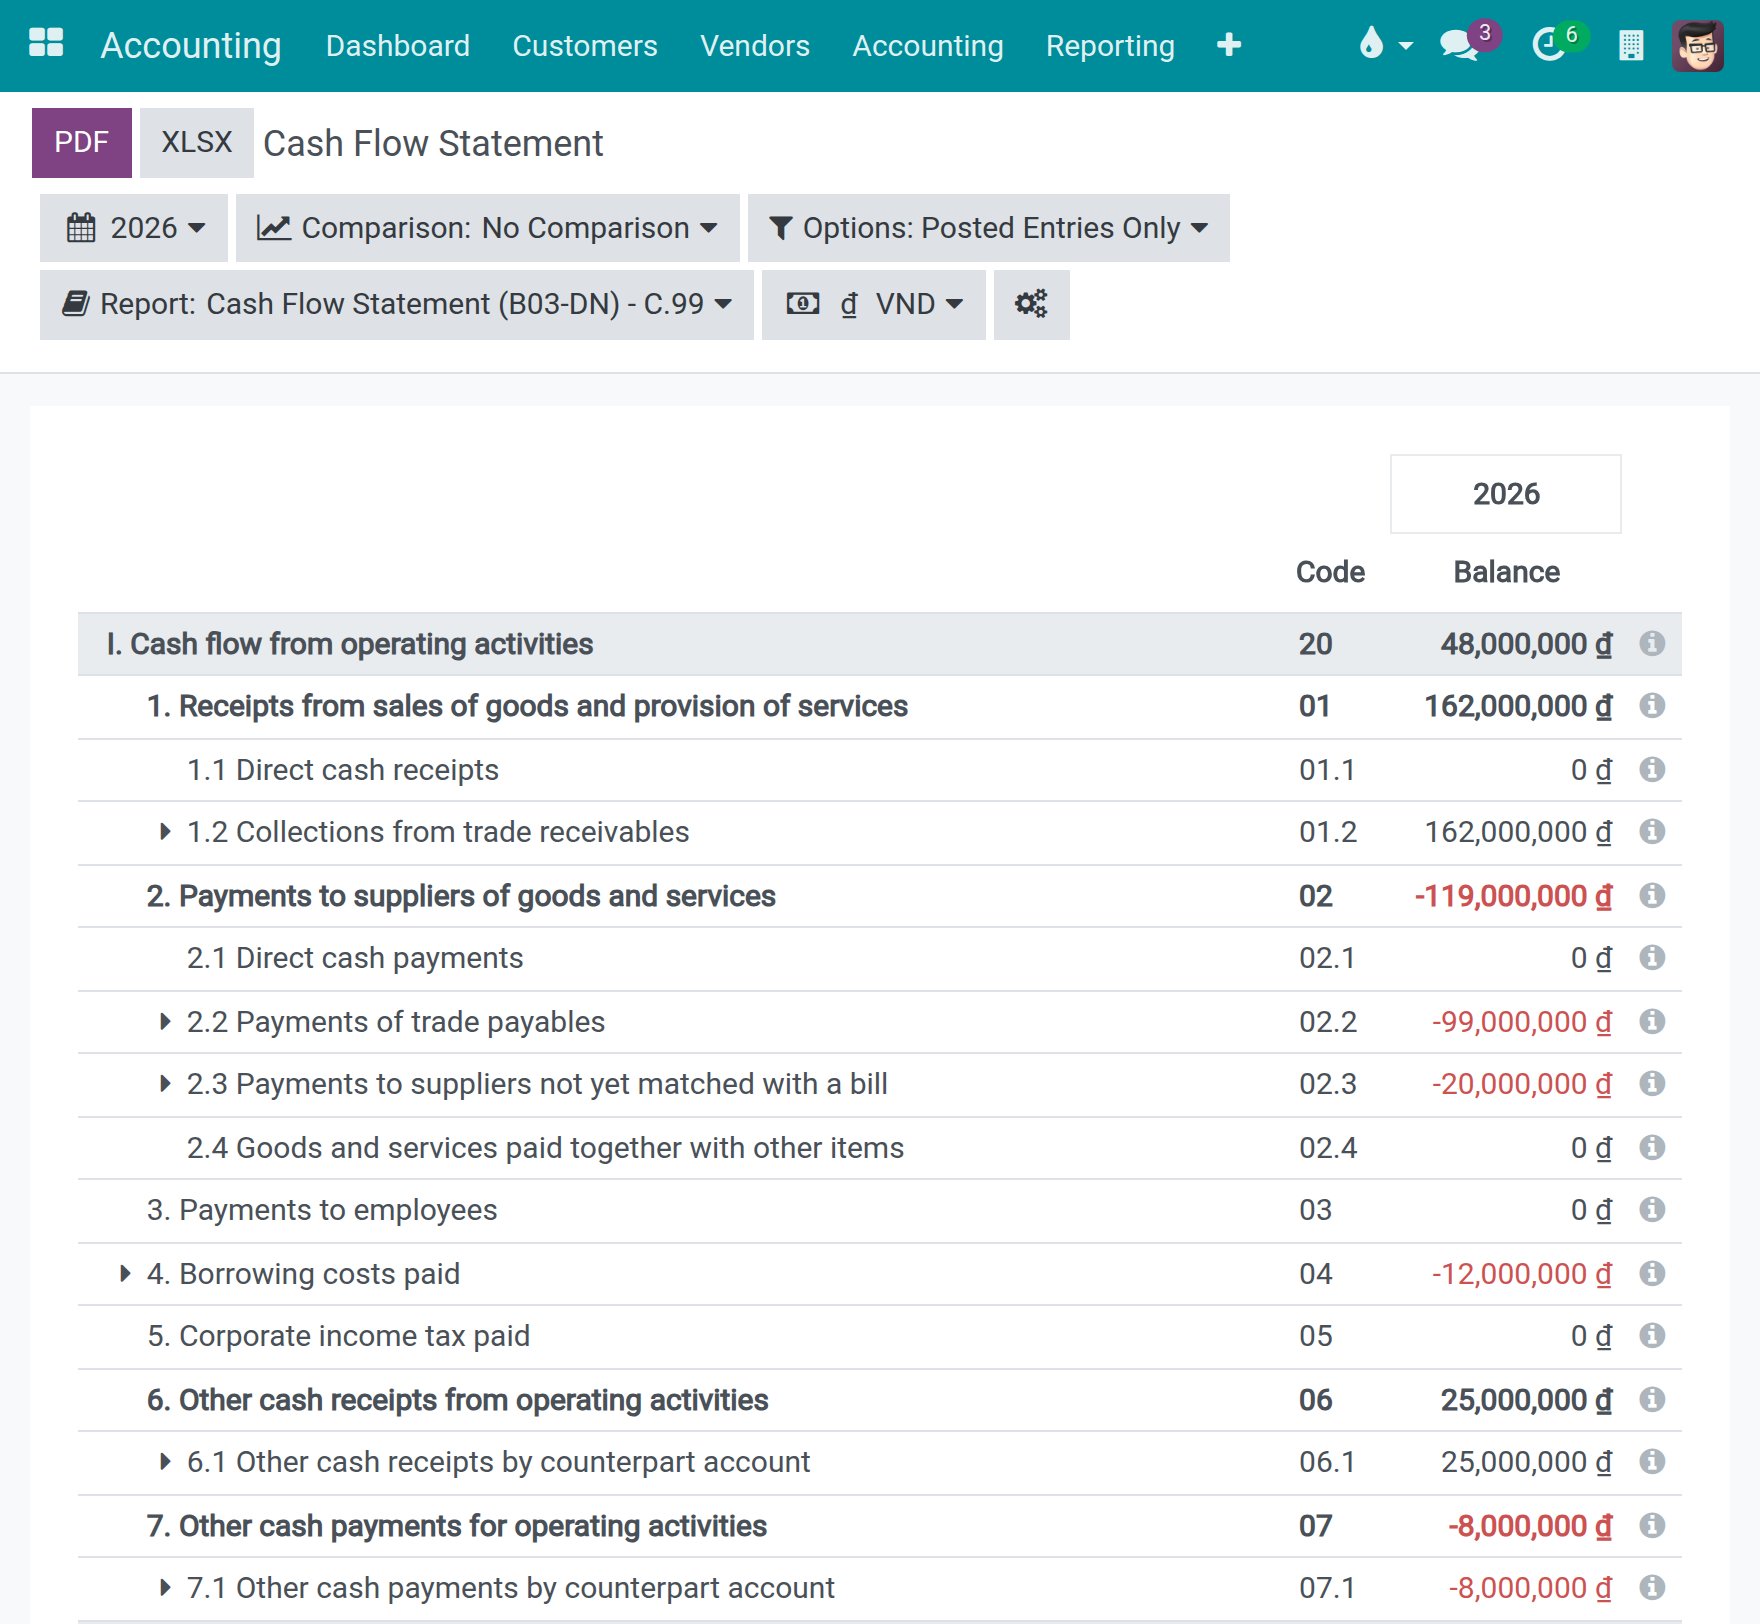
Customer prepayments. Money received from customers is on line 01 (Receipts from sales of goods and provision of services), whether it pays an invoice or is a prepayment received before the invoice exists. In the example, line 01.2 shows 162,000,000: an invoice payment of 132,000,000 and a customer prepayment of 30,000,000.
Supplier advances. Money paid to a supplier in advance, before the bill exists, is on line 02 (Payments to suppliers of goods and services). In the example, line 02.3 (Payments to suppliers not yet matched with a bill) shows -20,000,000 next to the -99,000,000 of the paid bills on line 02.2. On the B03-DNN form, the same figure is on line 02.4.
Interest on a loan. The interest paid on a loan is kept apart from its principal. When it is posted to the account 6351 (Borrowing costs), it is on line 04 (Borrowing costs paid): -12,000,000 in the example. The principal is on line 34, see below.
Other receipts and payments. Line 06 (Other cash receipts from operating activities) and line 07 (Other cash payments for operating activities) can be unfolded: lines 06.1 and 07.1 list the amounts by counterpart account, so you can see which account each receipt or payment came from. In the example, they are the bank statement lines that are not matched yet, which sit on the bank suspense account: 25,000,000 received and 8,000,000 paid out.

Investing activities
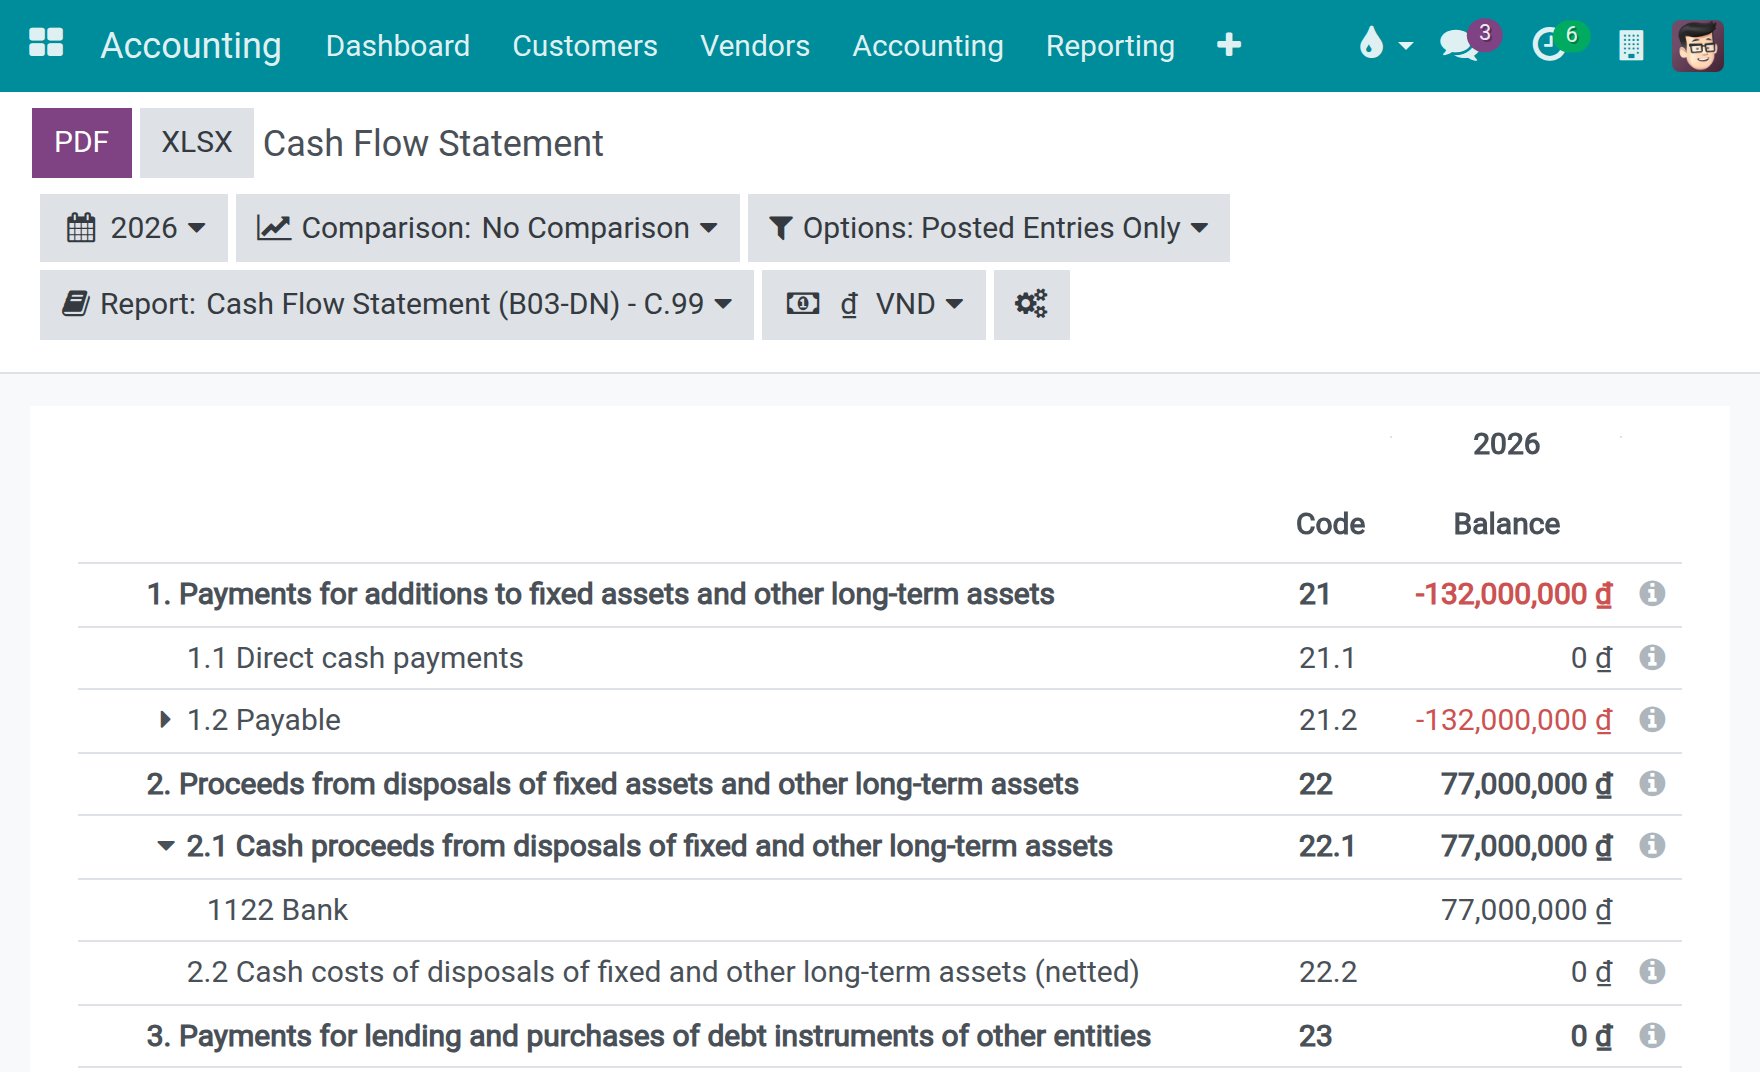
When you sell an asset with the Sell button of its form (Accounting > Accounting > Assets) and the customer pays the resulting invoice, the amount collected goes to line 22 (Proceeds from disposals of fixed assets and other long-term assets), not to the receipts from sales of goods: 77,000,000 in the example. This needs the module Accounting Reports - Vietnam Accounting - Fixed Asset Disposals.
On the Cash Flow Statement (B03-DNN) of Circular 133/2016/TT-BTC, lines 23, 24 and 25 carry the wording of that Circular: Payments for loans and equity investments in other entities, Recovery of loans and equity investments in other entities and Interest on loans, dividends and profits received.

Financing activities
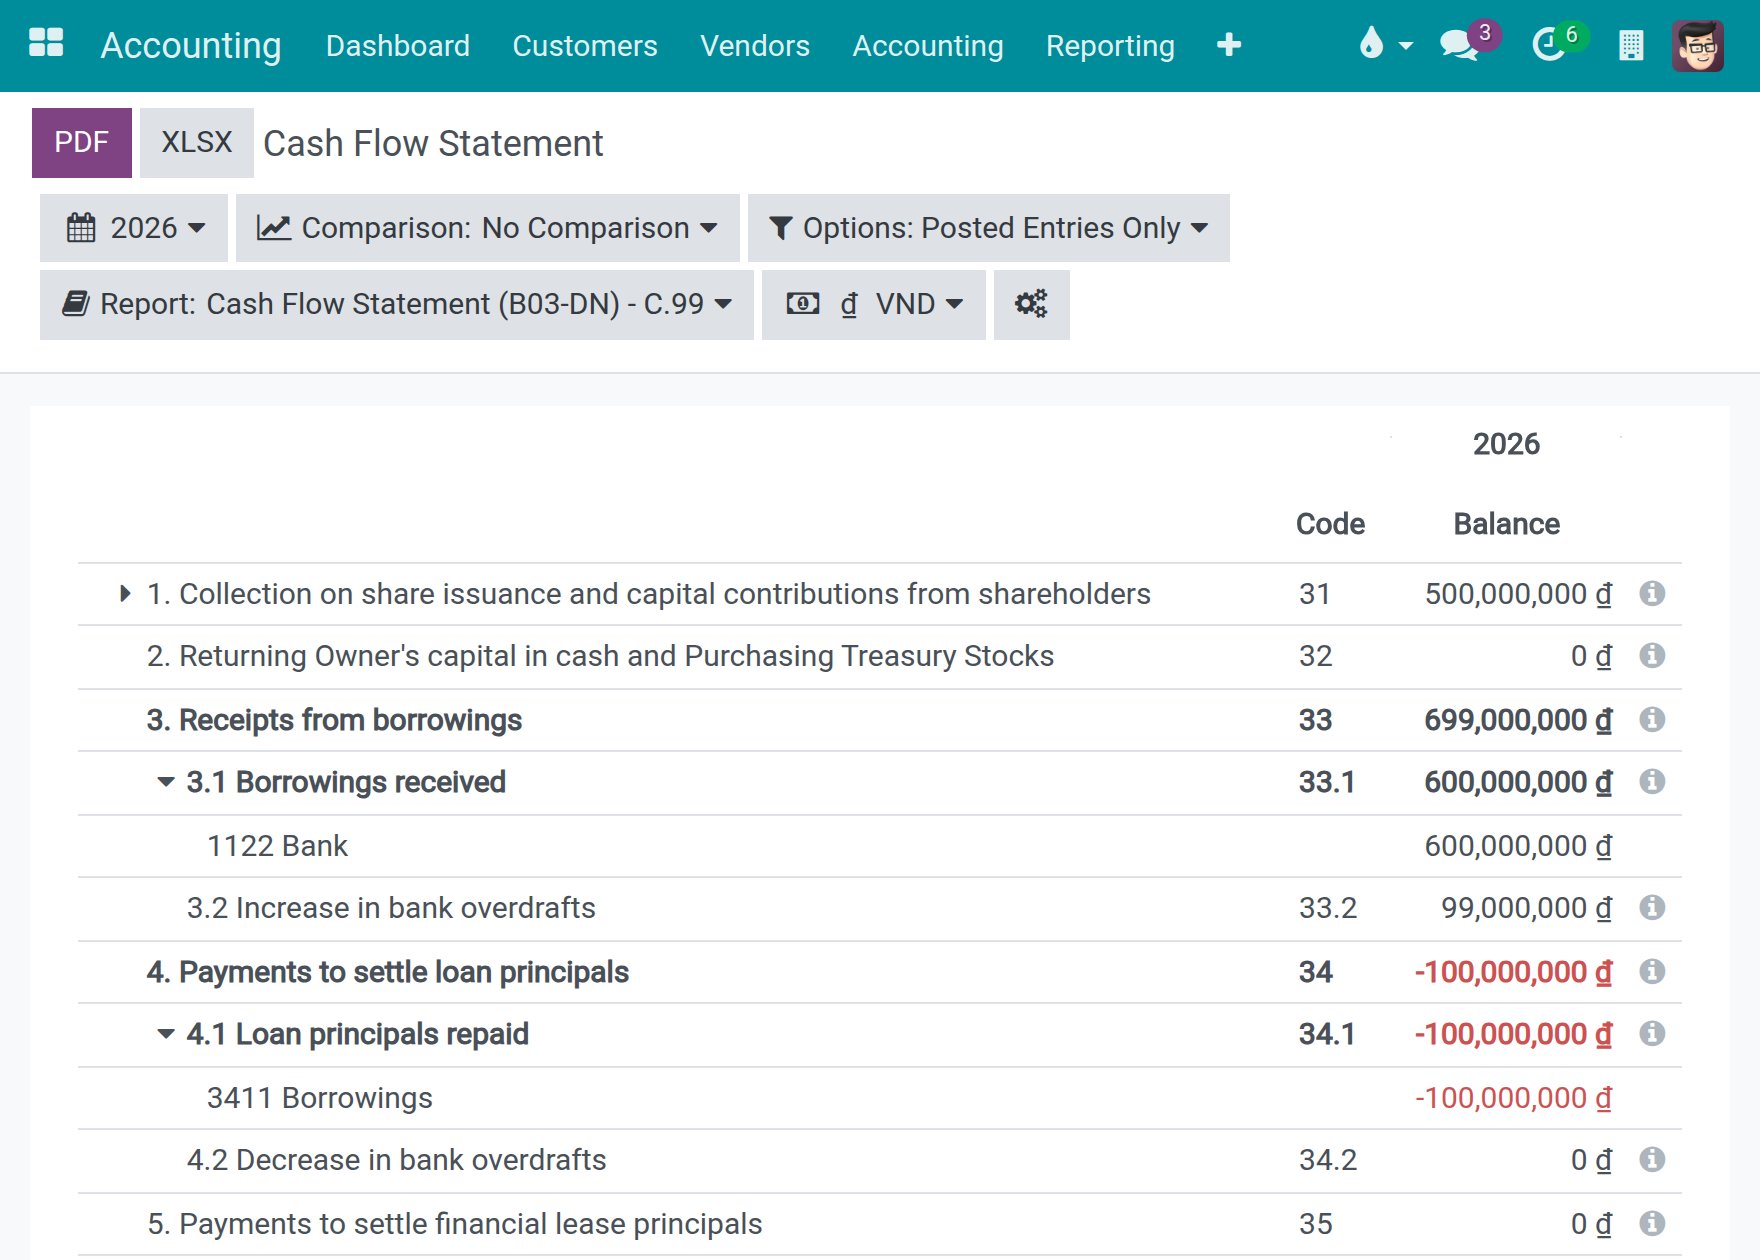
The principal of a loan repaid is on line 34 (Payments to settle loan principals), line 34.1 (Loan principals repaid): -100,000,000 in the example. Bank overdrafts move on two lines of their own: line 33.2 (Increase in bank overdrafts), under line 33 (Receipts from borrowings), and line 34.2 (Decrease in bank overdrafts), under line 34. In the example, line 33 is 699,000,000: 600,000,000 of borrowings received and 99,000,000 of increase in the bank overdraft.
Cash at the end of the period
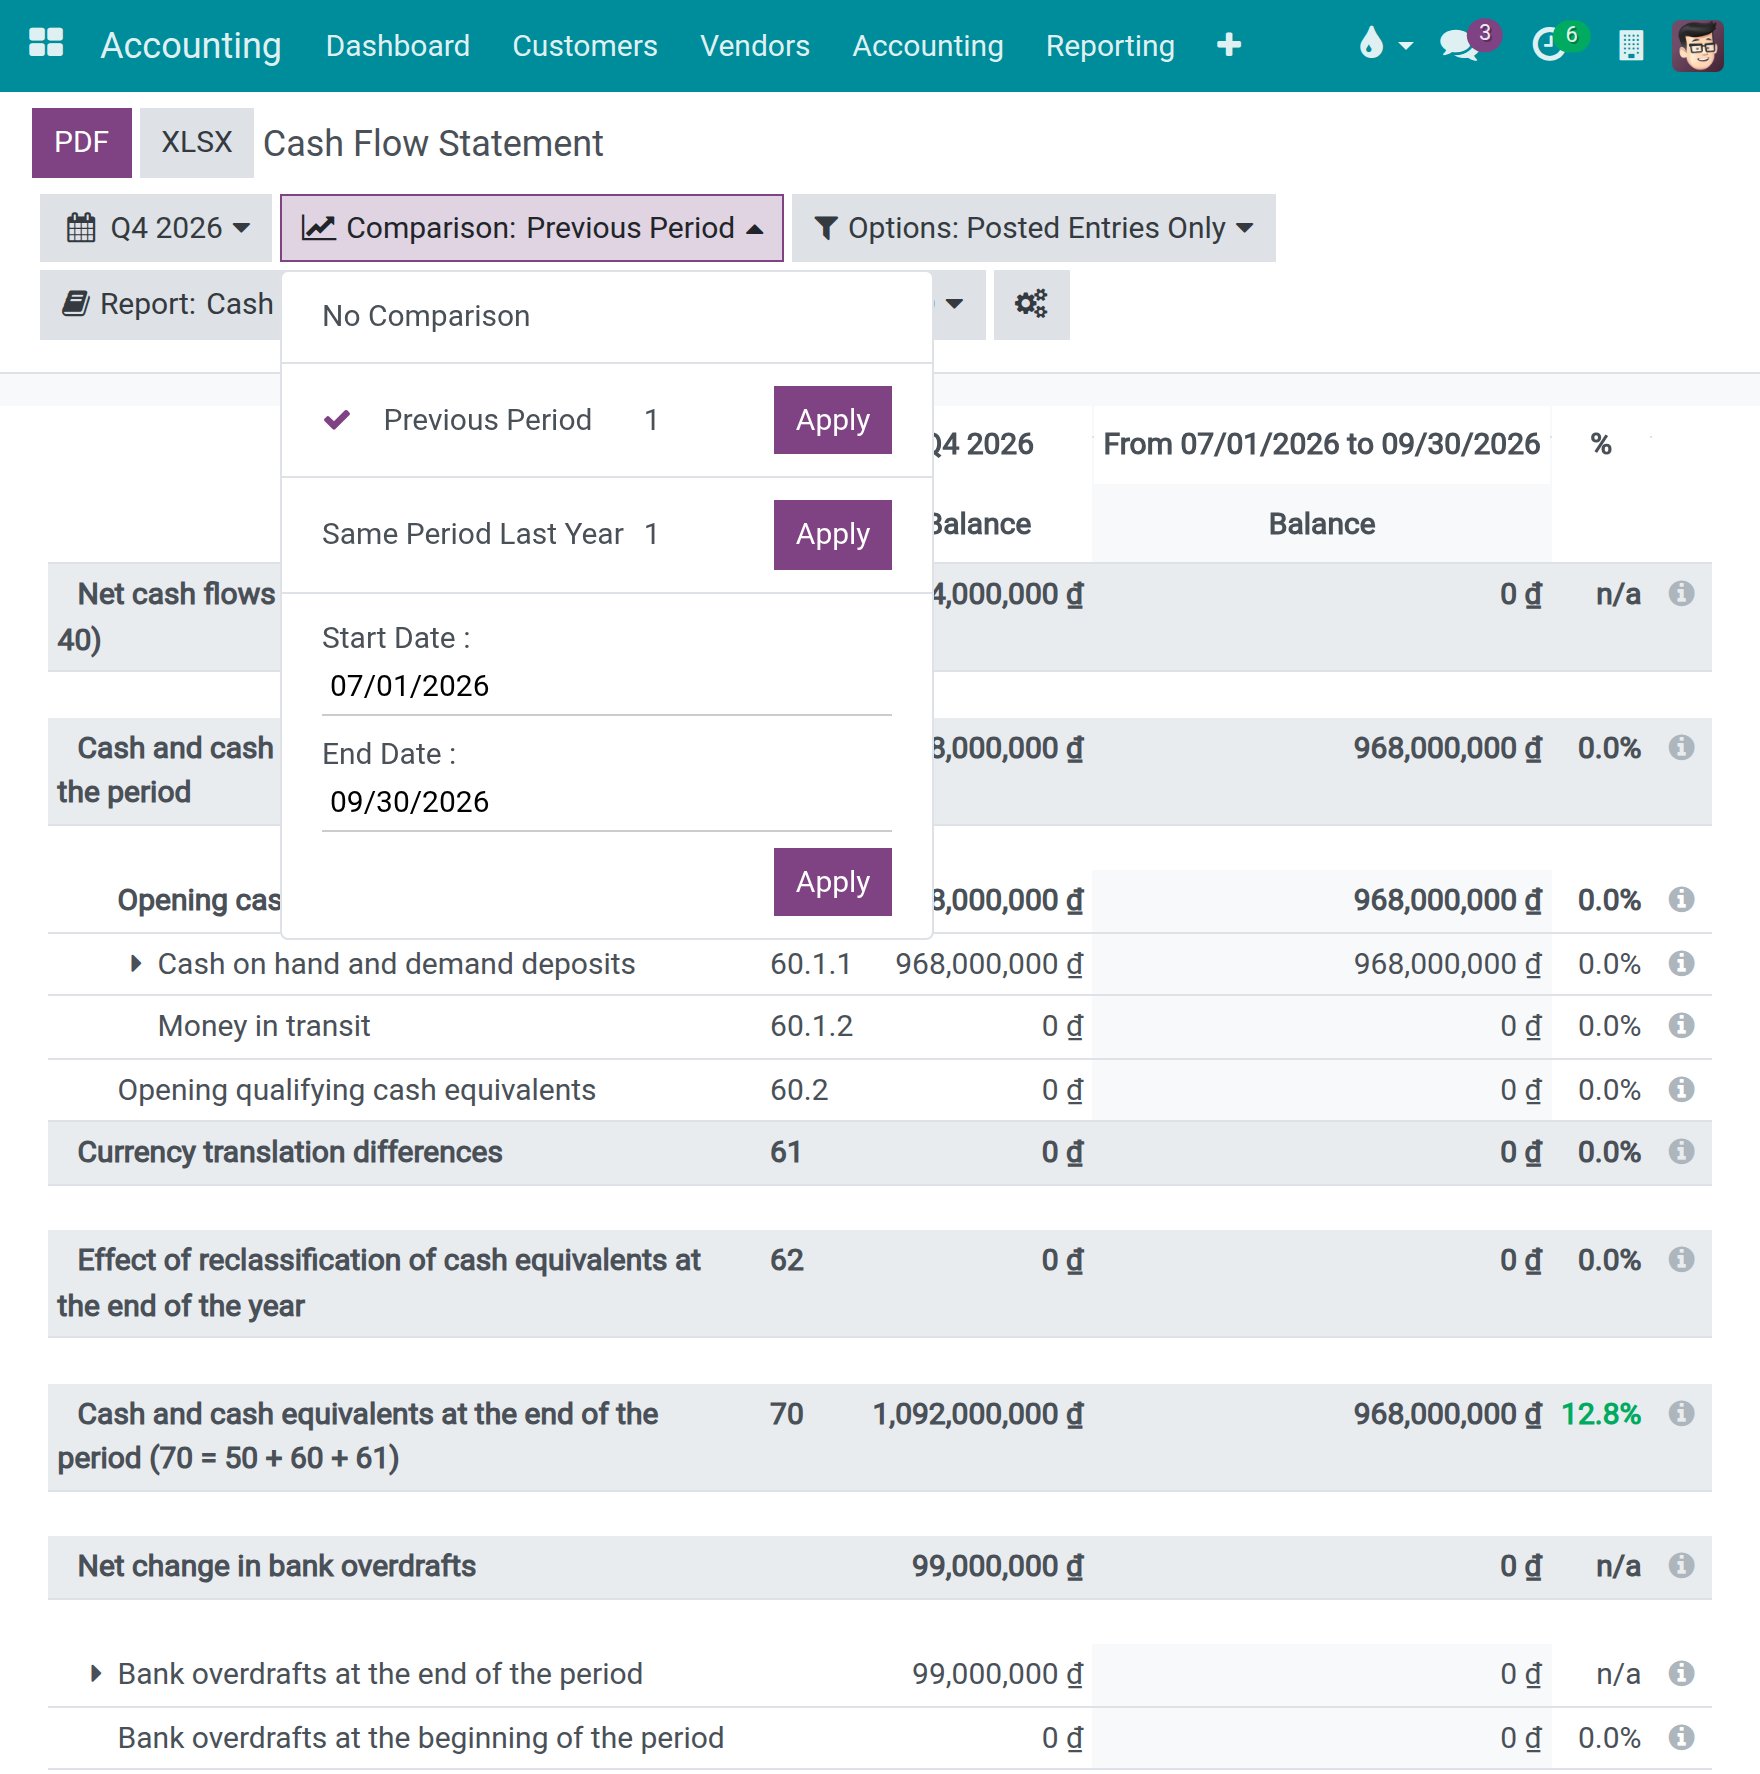
Information on this report is also displayed in different formats such as comparison between periods or detail tracking by journal.
Line 70 (Cash and cash equivalents at the end of the period) always equals line 110 of the Statement of Financial Position at the end of the same period, for any period you choose: a month, a quarter or a year. In the example, line 70 of the last quarter is 968,000,000, the same as line 110 of the Statement of Financial Position at the end of that quarter, which the comparison of the Statement of Financial Position above shows, and 1,092,000,000 for the current quarter.
Exchange rate differences are not mixed into the receipts and the payments: they are only on line 61 (Currency translation differences). Under line 70, the report also lists the net change in bank overdrafts and the bank overdrafts at the beginning and at the end of the period.
Trial Balance
Open Accounting > Reporting > Audit Reports > Trial Balance.
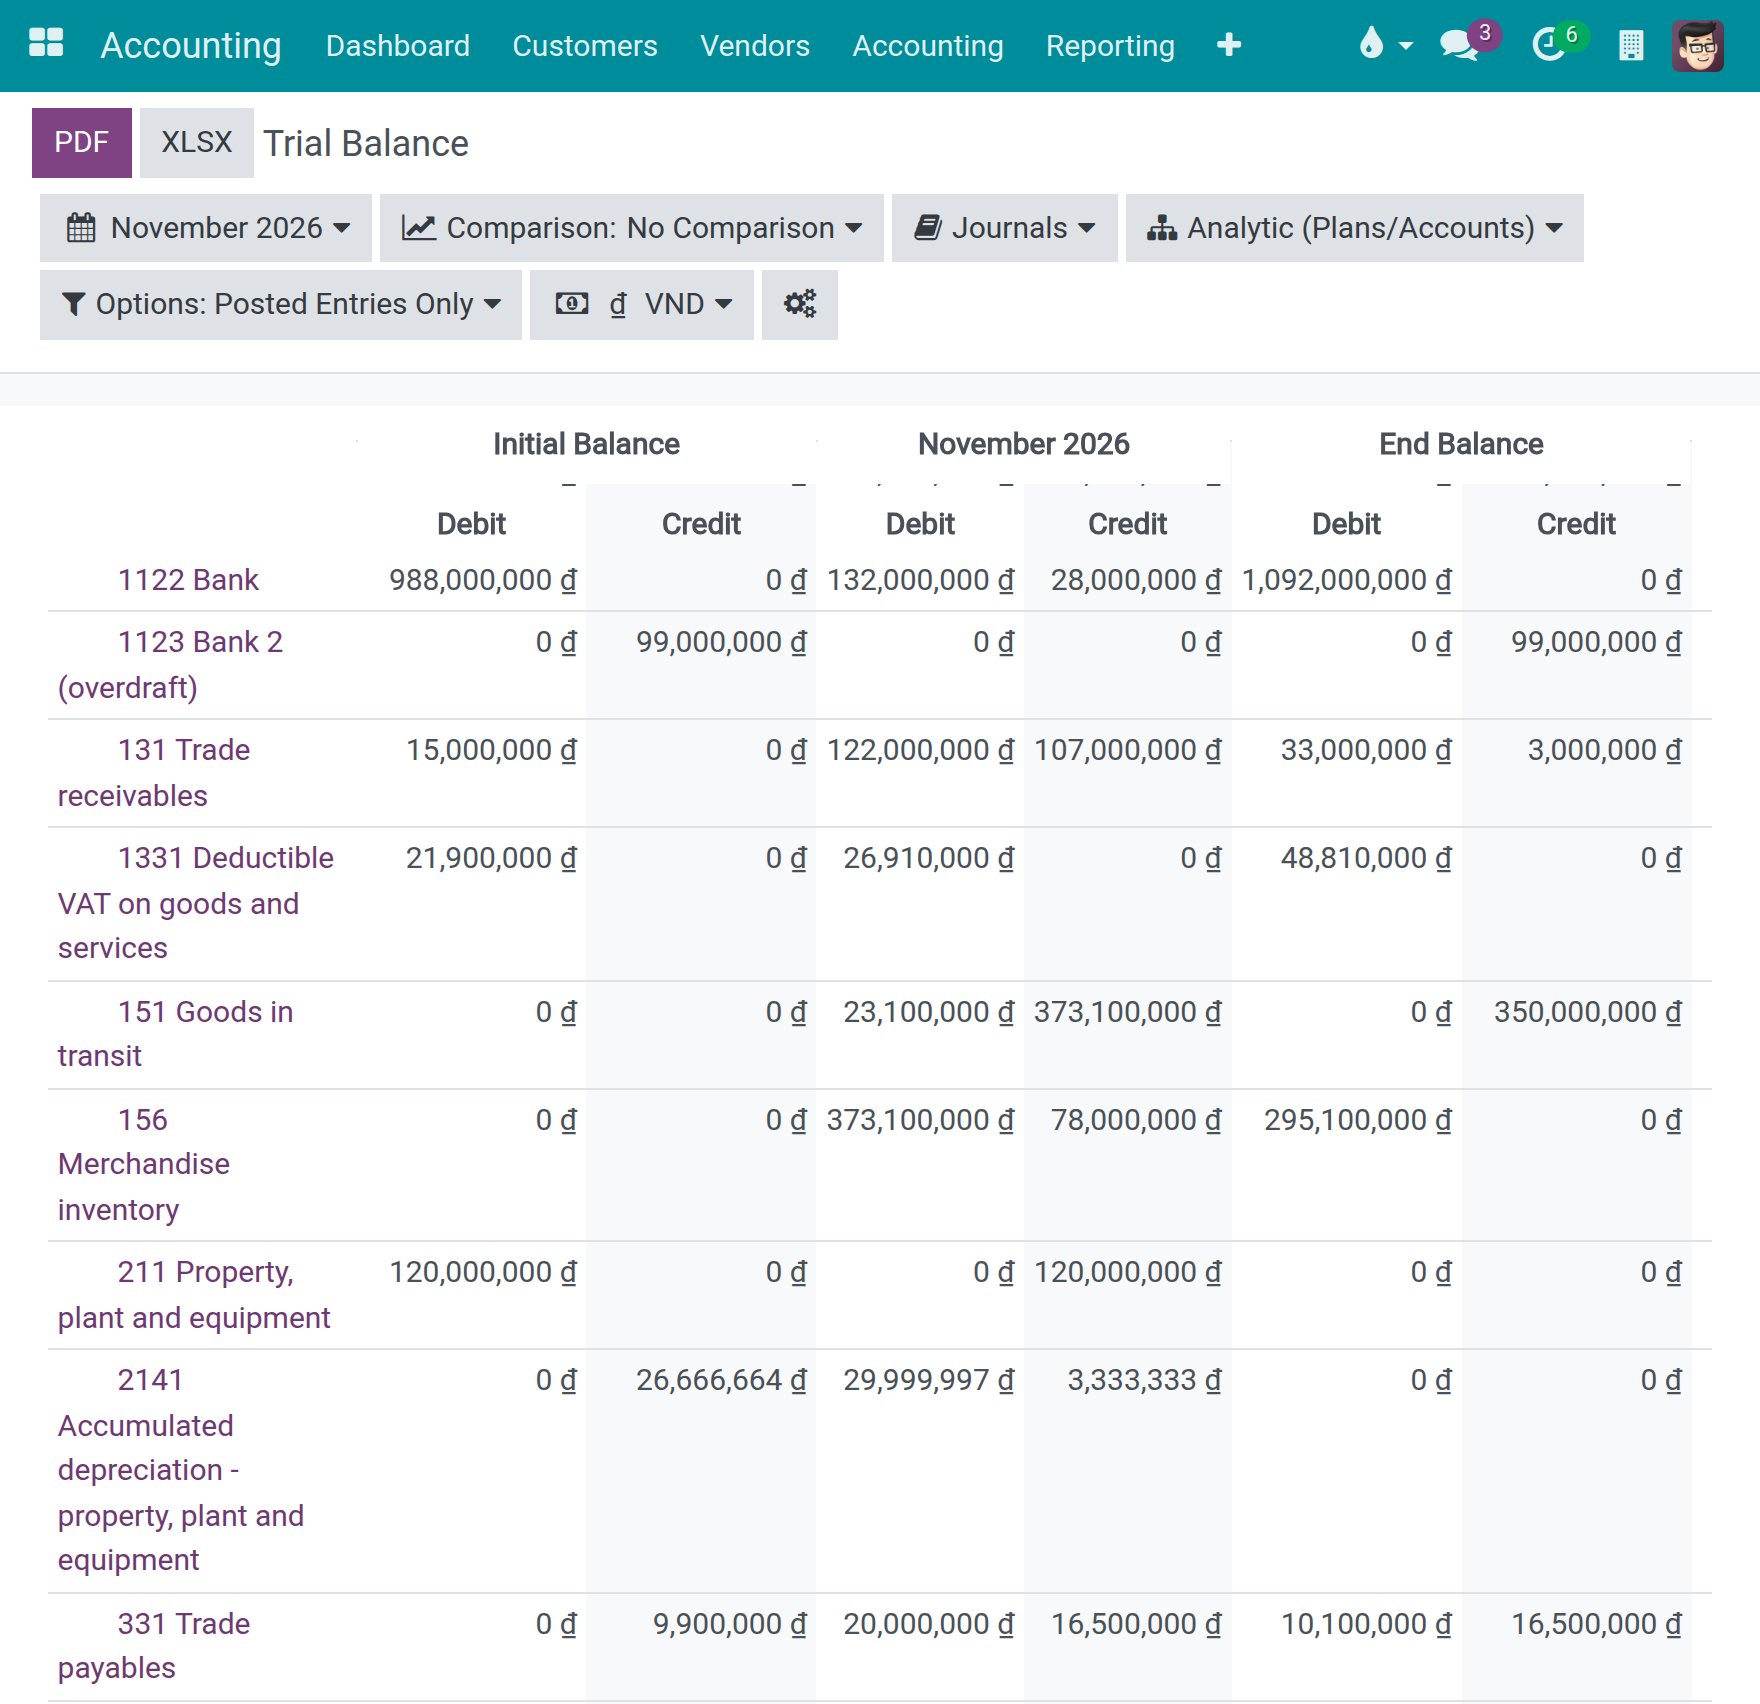
Receivable and payable accounts can carry a debit balance and a credit balance at the same time (customers who owe you and customers who paid in advance, for example). Accounts with the option Has balance at both debit and credit? switched on, such as 131 Trade receivables and 331 Trade payables (see Chart of Accounts), are balanced partner by partner, within each legal entity, before the totals are taken. The account therefore shows its debit balances in the Debit columns and its credit balances in the Credit columns, instead of one netted figure. All other accounts are balanced per company.
In the example, the end balance of the account 131 is a debit of 33,000,000 and a credit of 3,000,000, and the one of the account 331 is a debit of 10,100,000 and a credit of 16,500,000.
General Journal (S03a-DN)
Open Accounting > Reporting > Vietnam Accounting Reports > General Journal (S03a-DN) to print the general journal. For each journal line, the Counterpart Accounts column lists the codes of the accounts on the other side of the entry.
Print and export the reports
All the above reports can be downloaded in PDF and Excel formats for printing or saving purposes.
The accounting books and report forms are developed by Viindoo in accordance with the standards provided by the Vietnam Ministry of Finance, such as Account Detail Sheet, General Ledger, Trial Balance, etc. These reports are dynamic, the administrators can view them at any time, thereby accelerating the capture of opportunities as well as controlling the financial health of the business. For the lists of the sales and purchase invoices of a month or a quarter, see Sales and purchase invoice lists for Vietnamese companies.
See also
Related article
Optional module